In recent years, market turbulence and rising correlations between equities and bonds have challenged the efficacy of traditional allocations. The familiar 60/40 allocation model has shown its limits, as both asset classes fell together during downturns like 2022. To build resilience and tap new sources of return, investors must look beyond stocks and bonds.
By embracing alternative asset classes, you can reduce volatility, generate income, and hedge against inflation. This article explores why diversification matters, outlines the top alternatives, and offers practical guidance for building a balanced, future-ready portfolio.
Stocks can offer growth, but they come with elevated market volatility and concentration risks. Major themes such as AI and technology have driven valuations to historic highs, leaving limited room for error when sentiment shifts. Over-reliance on equities can expose investors to sharp drawdowns and extended recovery periods.
During the 2008–2009 financial crisis, conventional portfolios struggled as correlations spiked across asset classes. Similarly, bond yields have compressed, and government debt no longer provides the safe-haven returns it once did. Without new sources of diversity, portfolios face increased downside risk.
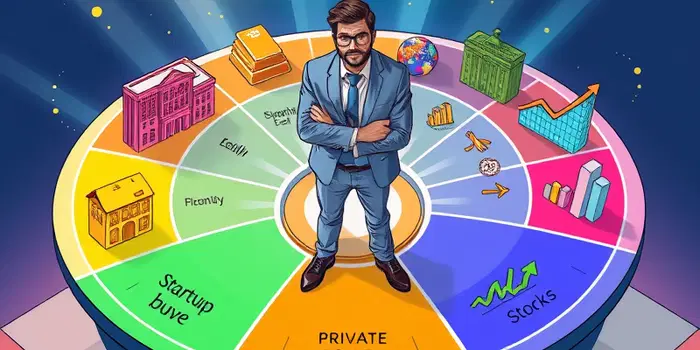
Below are seven categories of alternatives that retail investors can access, each offering unique risk-return profiles. Consider blending several to build a truly diverse, cross-asset portfolio across classes.
A practical framework might allocate 5–15% of a portfolio to alternatives for modest diversification, or up to 40% for a more institutional-style sleeve. Start by assessing your risk tolerance, time horizon, and income needs. Then select vehicles that align with your goals and liquidity requirements.
Many platforms now offer low minimums—some ETFs begin at €50—and interval or tender offer funds allow retail access to private markets with quarterly or monthly pricing windows. Regular rebalancing ensures you maintain your target allocation.
Alternative assets often come with higher fees, less transparency, and variable liquidity. Private equity and venture capital may lock up capital for 7–10 years. While alternatives can reduce overall volatility, they do not eliminate the risk of loss.
Correlation dynamics can shift during extreme market stress, so continuous monitoring and diversification within alternatives are essential. Conduct thorough due diligence on fund managers, fee structures, and tax implications before allocating significant capital.
As markets evolve, so must your portfolio. By integrating a measured allocation to alternative assets, you build a resilient, multi-dimensional investment strategy capable of navigating diverse economic environments.
Begin small, explore platforms with low minimums, and gradually expand your exposure. Over time, a thoughtfully diversified portfolio can deliver smoother returns, enhanced income, and greater protection against market turbulence.
References